Few institutions affect Americans’ finances as directly as the Federal Reserve, and few are as poorly understood. When news breaks that “the Fed raised rates” or “the Fed cut rates,” it can sound like a single switch that changes every interest rate at once. The reality is more interesting, and knowing how it works can help you make better decisions about debt and savings.
What the Fed is
The Federal Reserve is the central bank of the United States, created by Congress in 1913. It has three main parts:
- The Board of Governors in Washington, seven members nominated by the president and confirmed by the Senate for long, staggered terms. One serves as chair.
- Twelve regional Federal Reserve Banks, from Boston to San Francisco, which supervise banks and gather information about local economies.
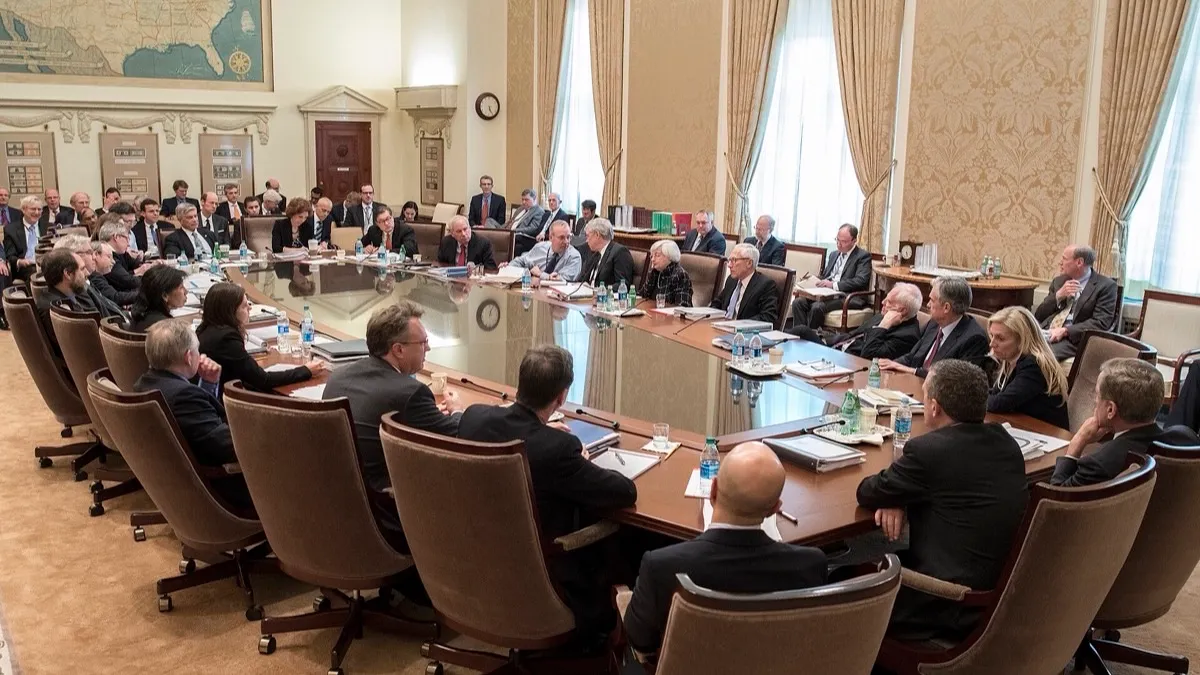
- The Federal Open Market Committee (FOMC), which sets monetary policy.
The FOMC has twelve voting members: the seven governors, the president of the Federal Reserve Bank of New York and four of the other eleven regional bank presidents, who rotate through one-year voting terms. It holds eight regularly scheduled meetings each year, and its decisions are announced in a statement, followed by a press conference with the chair.
The dual mandate
Congress has given the Fed two main goals for the economy: maximum employment and stable prices. These are often called the dual mandate. The Fed defines stable prices as inflation of 2% over time, measured by an index of consumer spending prices.
The two goals can pull in opposite directions. Raising rates can cool inflation but may slow hiring. Cutting rates can support jobs but risks letting inflation run hot. Much of the debate around each meeting is about which risk is bigger at that moment.
The main tool: the federal funds rate
The FOMC sets a target range for the federal funds rate, the interest rate banks charge each other for overnight loans. The Fed does not lend directly to consumers, but that short-term rate becomes the foundation for many others.
When the Fed raises its target, borrowing generally becomes more expensive across the economy, which tends to slow spending and inflation. When it cuts, borrowing gets cheaper, which tends to encourage spending and investment. The Fed can also buy or sell large amounts of government bonds, which influences longer-term rates.
How it reaches your money
Not every rate responds the same way or at the same speed:
- Credit cards: most card rates are variable and tied to the prime rate, which moves almost immediately with the Fed’s target. A cut or hike usually shows up on your statement within one or two billing cycles.
- Savings accounts and CDs: online savings accounts often adjust within weeks. Traditional banks tend to move slowly, especially when rates rise.
- Home equity lines and adjustable loans: these are usually tied to short-term benchmarks and follow the Fed fairly closely.
- Mortgages: 30-year fixed mortgage rates follow longer-term bond yields, especially the 10-year Treasury, which reflect expectations about inflation and growth over many years. That is why mortgage rates sometimes rise even after the Fed cuts, and sometimes fall before it acts.
- Car loans: these are influenced by the Fed but also by lenders’ competition and your credit profile.
Why the market moves before the Fed does
Investors constantly try to predict what the Fed will do next, and they price those expectations into bond yields and loan rates ahead of time. By the time a widely expected cut is announced, much of its effect may already be reflected in the market. Surprises, and changes in the Fed’s guidance about the future, often matter more than the decision itself.
What we think
The Fed’s decisions matter, but for most households they matter less than their own choices. A quarter-point cut saves very little on a credit card balance compared with paying the balance down. If you carry high-interest debt, waiting for the Fed is rarely the best plan.
The Fed is most useful as a signal. When it starts cutting, savings rates are likely to drift lower, so it can be a good moment to lock in a CD. When it is raising rates, adjustable-rate debt becomes riskier. Watch the direction of travel, not just the latest headline.